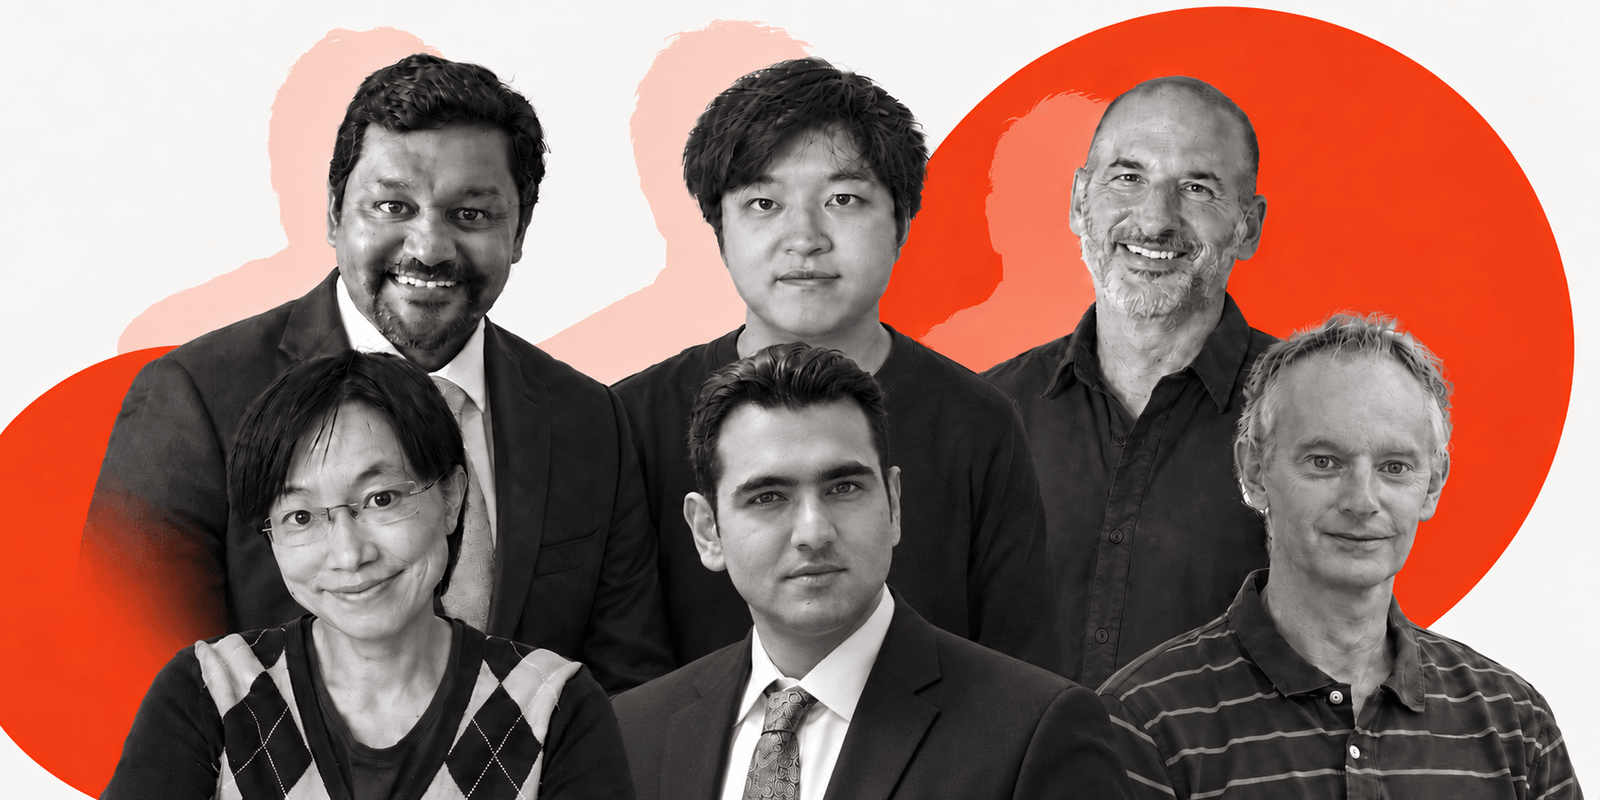
USC Viterbi and Stevens new faculty: Ajey Jacob (top left), Haowei Shi (top center), Itay Hen (top right), Morley Mao (bottom left), Sasan Razmkhah (bottom center) and Scott Mahlke (bottom right) The USC Stevens School of Computing and Artificial Intelligence welcomes six new faculty members whose research advances the frontiers of artificial intelligence, computing and
Video As A Sensor Market To 2035: Edge AI and Automated Inspection Fuel Growth – News and Statistics – IndexBox
Abstract
According to the latest IndexBox report on the global Video As A Sensor market, the market enters 2026 with broader demand fundamentals, more disciplined procurement behavior, and a more regionally diversified supply architecture.
The global Video As A Sensor market is entering a phase of structural expansion, with the forecast horizon 2026-2035 pointing to a compound annual growth rate of 12.4% and a market index reaching 285 by 2035 (2025=100). This growth is not merely a continuation of historical trends but a consequence of the fundamental shift from human monitoring to automated decisioning across industrial, automotive, and smart infrastructure applications. Video as a sensor—the use of video capture hardware and processing software as a primary data source for automated analysis, decision-making, and control—is becoming embedded in quality inspection, autonomous navigation, and security systems.
Demand is increasingly driven by system-level performance metrics such as latency and inference accuracy, shifting value upstream to integrated software and processing stacks. Qualification cycles and approved-vendor lists in industrial and automotive sectors lock in supply relationships for 5-7 year product lifecycles, creating a stable core for incumbents while raising barriers for new entrants. Manufacturing is consolidating around advanced packaging and wafer-level optics, concentrating technical capability and introducing supply chain dependencies.
The procurement model is fragmenting, with high-volume segments favoring distributor-led fulfillment and complex applications requiring direct technical sales. Geographically, design innovation is concentrated in specific hubs while volume manufacturing is dispersed for resilience. Regulatory frameworks are expanding to include data privacy, cybersecurity, and functional safety, adding compliance costs and accelerating consolidation.
This report provides a structured, commercially grounded analysis of these dynamics, offering decision-makers a clear view of end-use demand, design-in dynamics, manufacturing exposure, qualification burden, pricing architecture, and competitive positioning through 2035.
The baseline scenario for the Video As A Sensor market from 2026 to 2035 anticipates robust growth, with a CAGR of 12.4% and a market index of 285 by 2035 (2025=100). This outlook is supported by the accelerating adoption of automated optical inspection in manufacturing, the proliferation of smart cameras in security and surveillance, and the integration of video sensors in autonomous vehicles and robotics. The market is bifurcating into high-reliability, application-specific modules and commoditized, general-purpose sensors, creating distinct qualification pathways and margin structures.
Suppliers must choose their strategic lane, as hybrid approaches risk under-serving both performance-critical and cost-sensitive buyers. Demand is increasingly driven by system-level performance metrics rather than standalone sensor specifications, shifting value upstream to integrated software and processing stacks. This redefines competitive advantage, favoring players with vertical integration or deep software partnerships over pure hardware vendors. Qualification cycles and approved-vendor lists in industrial and automotive sectors act as a primary barrier to entry, locking in supply relationships for 5-7 year product lifecycles.
This creates a stable, high-margin core for incumbents but requires significant upfront investment in reliability engineering and customer support. Manufacturing is consolidating around advanced packaging and wafer-level optics, creating a supply bottleneck for leading-edge sensors and concentrating technical capability with a handful of specialized foundries and OSATs. This introduces a critical dependency for OEMs and elevates supply chain resilience to a top-tier design consideration. The procurement model is fragmenting: high-volume, cost-driven segments favor distributor-led fulfillment, while low-volume, high-complexity applications require direct technical sales and co-design support.
Channel strategy must therefore be segment-specific to capture value effectively. Geographic roles are crystallizing, with design innovation and algorithm development concentrated in specific hubs, while volume manufacturing and final assembly are geographically dispersed for resilience. Regulatory and standards frameworks are evolving from basic safety and EMC to encompass data privacy, cybersecurity, and functional safety, adding layers of compliance cost and design complexity. This disproportionately impacts smaller players and accelerates industry consolidation.
Overall, the baseline scenario assumes no major disruptive shocks, but sensitivity to supply chain disruptions and regulatory changes remains high.
Demand Drivers and Constraints
Primary Demand Drivers
- Shift from human monitoring to automated decisioning in industrial manufacturing, driven by the need for higher throughput and consistent quality.
- Proliferation of edge AI and deep learning inference at the sensor node, enabling real-time analytics and reducing latency.
- Stringent safety and quality regulations in automotive and industrial sectors, mandating automated inspection and functional safety compliance.
- Rising labor costs and skills shortages in manufacturing, accelerating the adoption of automated optical inspection systems.
- Increasing demand for smart surveillance and security systems in smart cities and critical infrastructure.
- Advancements in image sensor technology, including higher resolution, better low-light performance, and wafer-level optics.
Potential Growth Constraints
- High upfront investment and long qualification cycles for industrial and automotive-grade video sensors, delaying time-to-market.
- Data privacy and cybersecurity concerns, leading to stringent regulations and compliance burdens, especially in Europe and North America.
- Supply chain bottlenecks for advanced image sensors and specialized components, causing lead time variability and cost inflation.
- Lack of standardized interfaces and interoperability across different video sensor platforms, increasing integration complexity.
Demand Structure by End-Use Industry
Industrial Manufacturing (estimated share: 32%)
In industrial manufacturing, video as a sensor is primarily deployed for automated optical inspection (AOI), defect detection, and robot guidance. The segment is experiencing a structural shift from human visual inspection to automated systems driven by the need for higher throughput, consistent quality, and traceability. Manufacturers are integrating smart cameras with convolutional neural networks (CNNs) to perform real-time defect classification, reducing false positives and enabling adaptive process control. Demand-side indicators include factory automation spending, robot density, and the number of AI-based inspection systems installed.
Through 2035, the adoption will accelerate as AI models become more robust and edge computing enables low-latency inference. The integration of video sensors with industrial IoT platforms will allow predictive maintenance and closed-loop quality control. However, qualification cycles for industrial safety standards (e.g., IEC 61508) remain lengthy, locking in suppliers for 5-7 years. The trend is toward higher-resolution sensors, multi-camera setups, and 3D vision for complex assemblies. Major companies include Cognex, Basler, Keyence, Omron, and Teledyne. The segment’s growth is also supported by reshoring initiatives and the need for flexible manufacturing lines.
Current trend: Increasing adoption of automated optical inspection (AOI) and robotic guidance systems..
Major trends: Shift from rule-based vision to deep learning-based inspection, Integration of 3D vision for complex assembly verification, Adoption of edge AI for real-time defect detection, Growing use of multi-camera systems for large-volume inspection, and Increased demand for traceability and data logging.
Representative participants: Cognex Corporation, Basler AG, Keyence Corporation, Omron Corporation, and Teledyne Technologies.
Automotive and Transportation (estimated share: 24%)
The automotive and transportation sector is a key adopter of video as a sensor, primarily for advanced driver assistance systems (ADAS) and autonomous driving. Video sensors are used for lane keeping, traffic sign recognition, pedestrian detection, and surround view. The segment is driven by regulatory mandates for safety features (e.g., Euro NCAP, NHTSA) and the push toward higher levels of autonomy. Demand-side indicators include vehicle production volumes, ADAS penetration rates, and the number of cameras per vehicle. Through 2035, the adoption will expand from premium vehicles to mass-market models, with a growing number of cameras per vehicle (from 1-2 to 8-12).
The integration of video with other sensors (radar, LiDAR) in sensor fusion architectures will be critical. Qualification cycles are extremely stringent, with ISO 26262 functional safety and AEC-Q100 reliability standards. This creates high barriers to entry and long design-in cycles. Major companies include Sony, Samsung, onsemi, STMicroelectronics, and NVIDIA. The trend is toward higher resolution, HDR, and LED flicker mitigation. The segment is also seeing growth in commercial vehicles and off-highway applications. Current trend: Rapid growth in advanced driver assistance systems (ADAS) and autonomous vehicles..
Major trends: Increasing camera count per vehicle for 360-degree perception, Integration with sensor fusion for autonomous driving, Adoption of high-dynamic-range (HDR) and LED flicker mitigation sensors, Shift to centralized processing architectures, and Growing demand for in-cabin monitoring systems.
Representative participants: Sony Semiconductor Solutions, Samsung Electronics, onsemi, STMicroelectronics, and NVIDIA Corporation.
Security and Surveillance (estimated share: 20%)
In security and surveillance, video as a sensor is transforming from passive recording to proactive, intelligent monitoring. The segment is driven by the need for real-time threat detection, crowd management, and forensic analysis. Smart cameras with built-in AI are enabling edge-based analytics, reducing bandwidth and storage costs. Demand-side indicators include smart city investments, public safety budgets, and the number of AI-enabled cameras deployed. Through 2035, the adoption will accelerate with the proliferation of IoT and 5G connectivity, enabling real-time alerts and automated responses. The integration of video analytics with access control and alarm systems will create new value pools.
However, privacy regulations (e.g., GDPR) and cybersecurity concerns are restraining factors, requiring anonymization and secure data handling. The trend is toward higher resolution, multi-sensor cameras, and cloud-based video management systems. Major companies include Hikvision, Dahua, Axis Communications, Bosch, and Hanwha Techwin. The segment is also seeing growth in retail analytics and smart building applications. Current trend: Migration from passive recording to intelligent video analytics..
Major trends: Edge-based AI analytics for real-time alerts, Integration with IoT and 5G for smart city applications, Adoption of multi-sensor cameras (video, thermal, radar), Cloud-based video management and storage, and Growing demand for privacy-preserving analytics.
Representative participants: Hikvision, Dahua Technology, Axis Communications, Bosch Security Systems, and Hanwha Techwin.
Consumer Electronics and Smart Devices (estimated share: 14%)
Consumer electronics and smart devices represent a diverse segment for video as a sensor, including smartphones, augmented reality (AR) and virtual reality (VR) headsets, home robots, and smart appliances. In smartphones, video sensors are used for facial recognition, gesture control, and computational photography. The segment is driven by the demand for immersive experiences and intuitive user interfaces. Demand-side indicators include smartphone shipments, AR/VR headset sales, and the adoption of 3D sensing. Through 2035, the adoption will grow with the development of AR glasses and the metaverse, requiring low-power, high-resolution video sensors. The integration of AI for gesture and gaze tracking will be critical.
However, cost sensitivity and short product lifecycles are restraining factors, favoring commoditized sensors. The trend is toward smaller form factors, lower power consumption, and higher resolution. Major companies include Sony, Samsung, Apple, Qualcomm, and Intel. The segment is also seeing growth in smart home devices with video capabilities. Current trend: Integration of video sensors in smartphones, AR/VR, and home robots..
Major trends: Adoption of 3D sensing for facial recognition and AR, Integration of video sensors in AR/VR headsets for tracking, Growing use of video in home robots for navigation, Shift to under-display cameras in smartphones, and Increasing demand for low-power always-on sensing.
Representative participants: Sony Semiconductor Solutions, Samsung Electronics, Apple Inc, Qualcomm Technologies, and Intel Corporation.
Healthcare and Life Sciences (estimated share: 10%)
In healthcare and life sciences, video as a sensor is an emerging segment with applications in medical imaging, surgical robotics, and patient monitoring. Video sensors are used in endoscopes, surgical microscopes, and robotic surgery systems for real-time visualization and guidance. The segment is driven by the need for minimally invasive procedures and improved patient outcomes. Demand-side indicators include surgical procedure volumes, healthcare expenditure, and the adoption of robotic surgery systems. Through 2035, the adoption will grow with advancements in AI-assisted diagnosis and telemedicine. The integration of video with AI for real-time tissue classification and anomaly detection will be a key trend.
However, regulatory hurdles (e.g., FDA approvals) and high reliability requirements are restraining factors. The trend is toward higher resolution, 3D visualization, and fluorescence imaging. Major companies include Intuitive Surgical, Medtronic, Stryker, Olympus, and Karl Storz. The segment is also seeing growth in remote patient monitoring and tele-ICU applications. Current trend: Emerging applications in medical imaging, surgery, and patient monitoring..
Major trends: Adoption of 3D and 4K video in surgical visualization, Integration of AI for real-time surgical guidance, Growing use of video in telemedicine and remote monitoring, Development of disposable endoscopes with video sensors, and Increasing demand for fluorescence-guided surgery.
Representative participants: Intuitive Surgical, Medtronic, Stryker, Olympus Corporation, and Karl Storz.
Key Market Participants
Interactive table based on the Store Companies dataset for this report.
| # | Company | Headquarters | Focus | Scale | Note |
|---|---|---|---|---|---|
| 1 | Axis Communications | Sweden | Network video surveillance solutions | Global leader | Part of Canon Group |
| 2 | Bosch Security Systems | Germany | Video security & sensor technology | Large enterprise | Broad building tech portfolio |
| 3 | Hikvision | China | Video surveillance products & solutions | Global giant | Largest video surveillance vendor |
| 4 | Hanwha Vision | South Korea | Video surveillance & analytics | Large enterprise | Formerly Hanwha Techwin |
| 5 | Motorola Solutions (Avigilon) | USA | Video security & analytics | Large enterprise | Includes Avigilon brand |
| 6 | Dahua Technology | China | Video-centric smart IoT solutions | Global giant | Major surveillance provider |
| 7 | FLIR Systems (Teledyne FLIR) | USA | Thermal imaging & sensor systems | Large enterprise | Pioneer in thermal tech |
| 8 | Panasonic i-PRO | Japan | AI-powered security cameras & sensors | Large enterprise | Spun off from Panasonic |
| 9 | Verkada | USA | Cloud-managed building security sensors | Scale-up | Strong in modern enterprise |
| 10 | Milestone Systems | Denmark | Open platform video management software | Large enterprise | VMS market leader |
| 11 | Genetec | Canada | Unified security & VMS software | Large enterprise | Strong in public sector |
| 12 | Eagle Eye Networks | USA | Cloud video surveillance platform | Mid-market | Cloud VMS pioneer |
| 13 | Qognify | USA | Video management & situation management | Mid-market | Strong in critical incidents |
| 14 | IDIS | South Korea | Full-line video surveillance solutions | Large enterprise | DirectIP technology focus |
| 15 | Vivotek | Taiwan | Network camera solutions | Mid-market | Part of Delta Group |
| 16 | Agent Video Intelligence | USA/Israel | AI video analytics software | Mid-market | Pure-play analytics provider |
| 17 | BriefCam | USA/Israel | Video synopsis & analytics | Mid-market | Acquired by Canon |
| 18 | Ambarella | USA | AI vision semiconductor solutions | Mid-market | Key chip supplier for cameras |
| 19 | Seek Thermal | USA | Affordable thermal imaging sensors | Mid-market | Consumer & professional thermal |
| 20 | Rhombus Systems | USA | Cloud-native physical security platform | Scale-up | Modern, API-first platform |
Regional Dynamics
Asia-Pacific (estimated share: 38%)
Asia-Pacific dominates the Video As A Sensor market, driven by China’s manufacturing automation, Japan’s robotics leadership, and South Korea’s electronics ecosystem. Government initiatives like Made in China 2025 and smart city projects fuel demand. The region is also a hub for semiconductor fabrication and assembly, ensuring supply chain resilience. Direction: Strong growth.
North America (estimated share: 26%)
North America is a key market for video as a sensor, with strong demand from automotive ADAS, industrial inspection, and security. The U.S. leads in AI and software development, while Mexico is emerging as a manufacturing hub. Regulatory focus on safety and privacy shapes adoption. Direction: Steady growth.
Europe (estimated share: 22%)
Europe has a mature market for video sensors, driven by automotive safety regulations and industrial automation. Germany is a leader in factory automation and automotive engineering. The region is also at the forefront of data privacy regulations, influencing product design and deployment. Direction: Moderate growth.
Latin America (estimated share: 8%)
Latin America is an emerging market for video as a sensor, with growth driven by smart city projects, industrial automation, and security upgrades. Brazil and Mexico are the largest markets. Economic volatility and infrastructure gaps are challenges, but investment is increasing. Direction: Emerging growth.
Middle East & Africa (estimated share: 6%)
The Middle East & Africa region is a nascent market for video sensors, with demand concentrated in smart city initiatives (e.g., NEOM) and security surveillance. The region offers growth potential but faces challenges in infrastructure and skills. Investment in AI and IoT is rising. Direction: Nascent growth.
Market Outlook (2026-2035)
In the baseline scenario, IndexBox estimates a 12.0% compound annual growth rate for the global video as a sensor market over 2026-2035, bringing the market index to roughly 285 by 2035 (2025=100).
Note: indexed curves are used to compare medium-term scenario trajectories when full absolute volumes are not publicly disclosed.
For full methodological details and benchmark tables, see the latest IndexBox Video As A Sensor market report.

Related Posts